One of the most frequent questions asked when a client is considering taking an appeal from an adverse judgment or order is whether that judgment or order is stayed pending appeal. The answer, not surprisingly, is “it depends.” While the general rule is that perfecting an appeal stays proceedings in the trial court, including enforcement of the judgment or order, there are many, many, exceptions to that rule.
One such exception is a judgment or order for “money or the payment of money.” (CCP § 917.1) In such cases, a bond or undertaking is typically required to stay enforcement. The costs of such security can be significant. If you are using an admitted surety insurer, the amount of security required is 1 1/2 times the amount of the judgment. Obtaining a bond through an admitted surety will require that you have sufficient collateral to secure the bond, and sufficient funds to pay the associated premiums, which generally run between 1% and 3% of the total bond amount, per year. So, if you are appealing from a $1 million judgment, you will likely need $1.5 million in assets as collateral, and up to $30,000 per year for the premium.
Obviously, having a stay of enforcement in place pending appeal is preferred, if at all possible. Otherwise, if you pay out the judgment and then obtain a reversal, you are faced with the task of getting your money back. But what if you can’t afford to post a bond? Do you have options?
The answer is yes, you do. Code of Civil Procedure section 995.240 gives the trial court the discretion to waive the bond requirement for “indigent” parties who are “unable to obtain sufficient sureties.” And while parties who can afford lawyers and/or have insurance for their defense may not immediately come to mind as “indigent,” a recent published decision from the Third District Court of Appeal makes it clear that there is no fixed definition of “indigent” and that under this statute, an “indigent” party is simply “any person who is unable to obtain sufficient surety, not just a person who is destitute.” (Guzman v. Superior Court (2026) 122 Cal.App.5th 1286, 1291.)
In Guzman, the defendant sought to appeal a $20 million personal injury judgment. With insufficient assets to secure the necessary $30 million bond, he sought relief under CCP § 995.240, and the trial court lowered the amount of the bond to $1.25 million. The plaintiff sought a petition for writ of mandate or prohibition, and after issuing an order to show cause, the appellate court denied the petition. The court held the statute gives the trial court the discretion to waive the bond if it determines the principal cannot obtain sufficient sureties because they are indigent, and that it is the principal’s actual ability to pay that guides the court’s assessment of indigency. In other words, one need not be destitute to be considered “indigent” under this statute. The trial court did not abuse its discretion where it held a hearing and took evidence on the principal’s financial situation, and the cost of an appellate bond at various levels, before reducing the amount of the bond required. At the heart of the Guzman decision was the court’s concern with access to justice. If a litigant cannot afford a bond, “considerations of immediate judgment enforcement will necessarily impact [their] strategy in seeking and executing an appeal.” (Guzman, at p. 1296.) “[L]itigants who can afford a bond will be in a better position to assert their rights than those who cannot.” (Ibid.) If you or your client are in a position where the cost of the required bond is out of reach, don’t neglect to pursue a waiver or reduction of the bond amount under section 995.240, and to cite Guzman in support of your motion.
California is expanding regulatory oversight of healthcare transactions affecting cost, access, equity, and competition. Deal parties should evaluate early whether notice or filing obligations arise under the Office of Health Care Affordability (“OHCA”), the California Department of Insurance (“DOI”), or the California Department of Managed Health Care (“DMHC”).
Office of Health Care Affordability
OHCA now has authority to receive notice of certain material healthcare transactions involving entities doing business in California and, in some cases, to conduct a cost and market impact review (“CMIR”).
Covered transactions include mergers, acquisitions, affiliations, joint ventures, asset transfers, governance changes, and other arrangements involving a transfer of control or material operational change. Depending on the transaction’s size and nature, OHCA may require only a pre-transaction notice or may conduct a more extensive CMIR.
Covered transactions require at least 90 days’ advance written notice before closing. Filing obligations are triggered when a healthcare entity with $25 million or more in annual California revenues is involved, with additional thresholds depending on transaction type. The review process can materially affect timelines, create execution risk, require substantial document production, and influence closing conditions, outside dates, and regulatory cooperation covenants. Parties should assess early whether a may trigger a CMIR.
OHCA’s jurisdictional analysis is highly fact-specific. Whether a particular entity qualifies as a covered healthcare entity, or whether an arrangement constitutes a material transaction, may require detailed review of organizational structure, revenue, licensure, service lines, and control rights. OHCA analysis should now be a standard part of diligence for California healthcare transactions.
When Are DOI or DMHC Filings Required?
DOI filings may be triggered where the transaction involves an insurance-licensed entity, a health insurer holding company, or a change of control of an insurer. DMHC filings may arise where the transaction involves a licensed healthcare service plan or an entity regulated under the Knox-Keene Act, including transactions affecting plan operations, governance, provider networks, or the assumption of risk.
For both agencies, parties should not assume a transaction escapes regulatory review merely because the regulated entity is not the direct target. Upstream ownership changes, restructurings, intercompany transactions, and affiliated-party dealings may all trigger filing requirements depending on control concepts and materiality thresholds.
DOI and DMHC review can substantially affect deal timing and closing mechanics. Filings may require detailed disclosures on ownership, governance, financial condition, business plans, and competitive effects, and may involve waiting periods, supplemental inquiries, or formal approval requirements. Where DMHC is involved, the regulator may also focus on operational continuity, enrollee protections, solvency, and network adequacy under the Knox-Keene Act. Counsel should coordinate early with regulatory specialists to determine filing requirements and align transaction documents with expected review timelines.
What Additional Issues Arise When DMHC-Licensed Plans Are Involved?
Where a DMHC-licensed healthcare service plan is involved, DMHC may scrutinize the transaction’s effect on plan administration, provider contracting, utilization management, and delegated functions.
DMHC filing requirements can also arise in management agreements, delegated arrangements, and transactions involving risk-bearing organizations (RBOs), which may not be immediately apparent from the deal’s corporate structure alone.
Even when a deal is structured as a corporate transaction, DMHC may examine its practical effect on downstream regulated plan operations and delegated arrangements, which can shape both the filing’s substance and the regulator’s review timeline.
What Should Healthcare Dealmakers Do Now?
Against this backdrop, healthcare transaction parties should approach California deals with a more integrated regulatory strategy. Early-stage diligence should evaluate not only corporate, licensure, reimbursement, fraud and abuse, and antitrust issues, but also whether the proposed transaction triggers OHCA notice requirements or requires DOI or DMHC filings.
This analysis should begin before a letter of intent is finalized. Among other things, parties should assess: the identity and licensure status of relevant entities; whether control is changing directly or indirectly; whether management, governance, or contracting rights could confer control; whether risk-bearing or payer functions are implicated; and whether the anticipated timeline accounts for pre-closing notice, review, or regulatory approval periods.
California’s evolving oversight of healthcare business transactions reflects a broader policy trend toward increased review of deals that may affect affordability, competition, and access to care. The new OHCA notice requirements, together with existing DOI and DMHC filing regimes, make early regulatory assessment more important than ever. Stakeholders in California healthcare transactions should work closely with counsel to evaluate how existing and emerging requirements apply to proposed structures and strategic objectives.
Aaron R. Claxton leads the Wilke Fleury LLP healthcare team, advising health plans, insurers, and providers on complex legal, regulatory, compliance, and business matters in California.
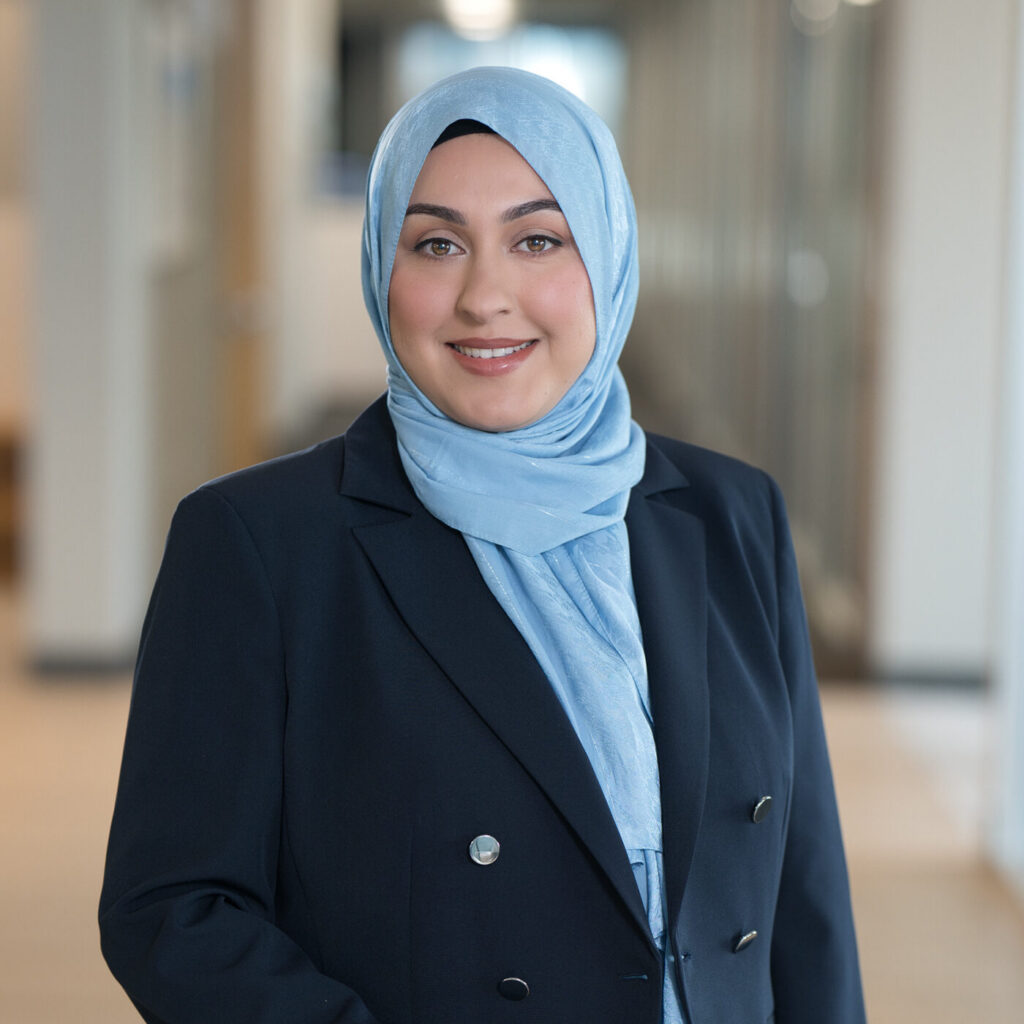
Wilke Fleury is pleased to announce that Mena M. Arsalai has been named Of Counsel with the firm.
A member of Wilke Fleury’s Healthcare practice, Mena advises healthcare providers and organizations on regulatory, transactional, and operational matters. Her practice also increasingly focuses on helping physicians navigate employment agreements, career transitions, business opportunities, and other significant professional decisions throughout their careers.
“Mena has become integral to the Healthcare team and a trusted advisor to our clients,” said Aaron Claxton, Partner “She brings sound judgment, a practical approach, and a genuine commitment to helping physicians and healthcare organizations make informed and strategic decisions. We’re pleased to recognize her many contributions with this new role.”
Mena’s new title reflects her experience, contributions to the firm, and continued commitment to serving clients.
Congratulations, Mena!
This website uses cookies to improve your experience. We'll assume you're okay with this, but you can opt-out if you wish. Cookie SettingsACCEPT
Privacy & Cookies Policy
Privacy Overview
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. This category only includes cookies that ensures basic functionalities and security features of the website. These cookies do not store any personal information.
Any cookies that may not be particularly necessary for the website to function and is used specifically to collect user personal data via analytics, ads, other embedded contents are termed as non-necessary cookies. It is mandatory to procure user consent prior to running these cookies on your website.