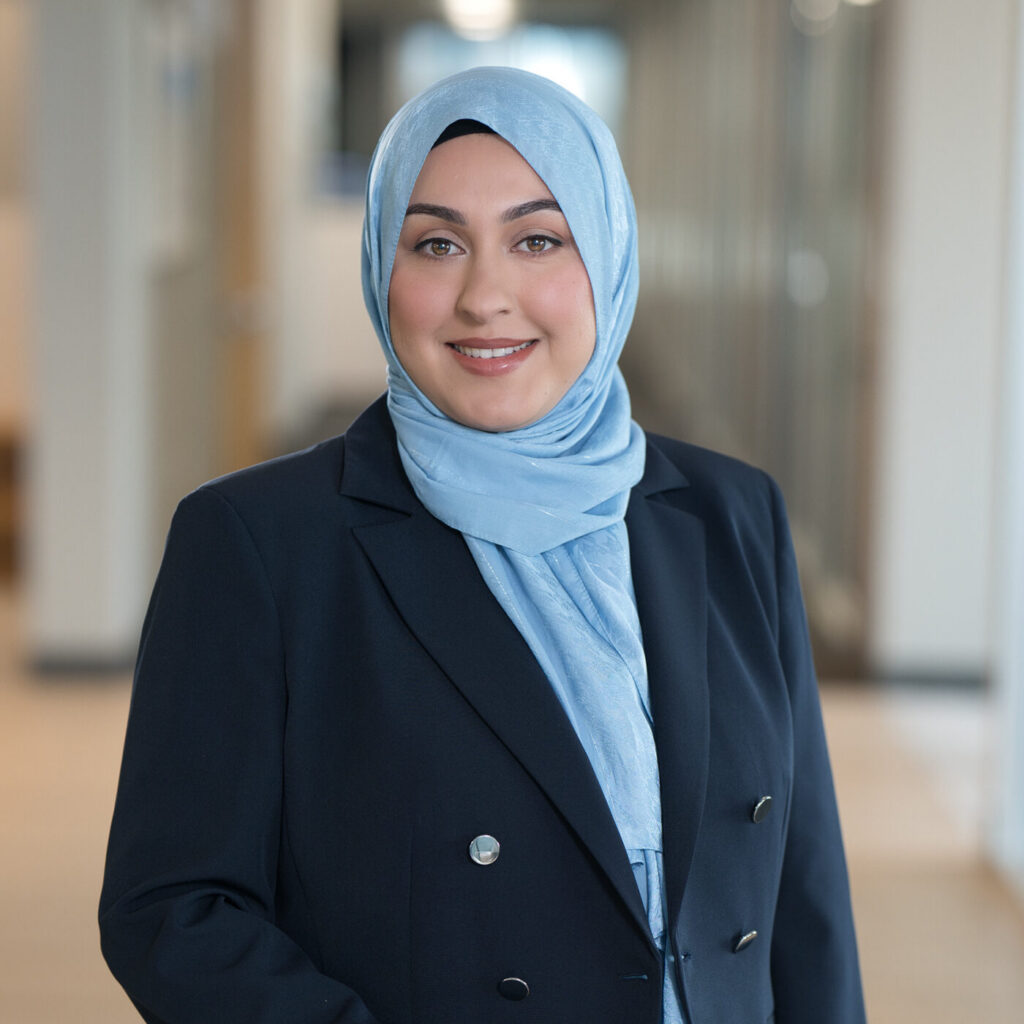
Wilke Fleury is pleased to announce that Mena M. Arsalai has been named Of Counsel with the firm.
A member of Wilke Fleury’s Healthcare practice, Mena advises healthcare providers and organizations on regulatory, transactional, and operational matters. Her practice also increasingly focuses on helping physicians navigate employment agreements, career transitions, business opportunities, and other significant professional decisions throughout their careers.
“Mena has become integral to the Healthcare team and a trusted advisor to our clients,” said Aaron Claxton, Partner “She brings sound judgment, a practical approach, and a genuine commitment to helping physicians and healthcare organizations make informed and strategic decisions. We’re pleased to recognize her many contributions with this new role.”
Mena’s new title reflects her experience, contributions to the firm, and continued commitment to serving clients.
California’s managed care organization (“MCO”) tax has been rewritten once again, and this time the change was not optional. On June 29, 2026, Governor Newsom signed Senate Bill 125, chaptered as Chapter 24 of the Statutes of 2026, restructuring the tax that health plans doing business in California pay to help fund Medi-Cal. The bill was necessary because the version of the tax California had been counting on no longer complied with federal law.
Some background helps explain how the state got here. Medicaid is funded jointly by the federal government and the states, and federal regulations allow states to impose taxes on health care providers, including managed care plans, to help cover the state’s share of program costs. States can then use that revenue to draw down additional federal matching funds. To qualify, a provider tax must be broad based, uniformly imposed, and free of hold harmless provisions that effectively guarantee the taxed entities get their money back. Every state but Alaska uses some version of this tool.
California has relied on an MCO tax in various forms since 2005, and voters made the tax permanent in November 2024 through Proposition 35 (“Prop. 35”), which also dedicated the revenue to raising Medi-Cal provider reimbursement rates. The version of the tax in place at that time used a tiered structure that charged Medi-Cal managed care plans a substantially higher rate than commercial plans. Under that structure, the middle tier applied to Medi-Cal enrollees reached roughly $182.50 per enrollee, compared to just a few dollars for non-Medi-Cal enrollees in the same tier.
That structure ran into trouble eight months later. On July 4, 2025, President Trump signed the One Big Beautiful Bill Act (“OBBBA”), which imposed new federal limits on how states can use provider taxes, including a rule barring any tax that applies a higher rate to Medicaid business than to non-Medicaid business. California’s tiered MCO tax did precisely that, and it fell out of compliance the moment the OBBBA was signed. Without a fix, the state stood to lose access to billions of dollars in federal Medi-Cal matching funds.
SB 125 is that fix. For calendar years 2027 through 2029, the bill assesses a flat tax of $8.85 per enrollee per month on MCOs, applied equally whether the enrollee is in Medi-Cal or a commercial plan. It also creates a Medi-Cal Stability Fund and continuously appropriates the tax revenue to the Department of Health Care Services (“DHCS”) to support Medi-Cal expenditures, and it gives DHCS authority to adjust the taxing tiers and schedule going forward. Collection will not begin until January 1, 2027, or until the necessary federal approval comes through, whichever is later.
The dollar figures tell the rest of the story. Because the new tax is flat rather than tiered, commercial and other non-Medi-Cal plans that previously paid only a few dollars per enrollee per month will now pay the same $8.85 that Medi-Cal plans pay. According to the Senate Rules Committee’s analysis, the restructured tax is projected to generate general fund support of roughly $575 million in fiscal year 2026-2027, $2.3 billion in each of the following two years, and $1.7 billion in 2029-2030. That is a fraction of the nearly $8 billion a year the Prop. 35 version of the tax was projected to raise, and it is closer to what the tax generated before Prop. 35 passed. The California Association of Health Plans has estimated the flattened rate will add roughly $100 per year to the cost of coverage per covered person, a cost that plans are expected to pass through in premiums.
For health plans operating in California, the practical effect will likely show up in two places over the next few years: rate filings, as plans account for the new assessment in setting premiums, and reserves, as commercial and other non-Medi-Cal plans absorb a cost they did not previously face at this level. Plans that had little or no exposure under the old tiered structure should not assume that will continue once collection begins. The federal approval timeline is also worth watching, since it determines when the $8.85 assessment actually takes effect, and DHCS’s authority to adjust the taxing tiers and schedule means the mechanics of the tax could still shift before collection starts.
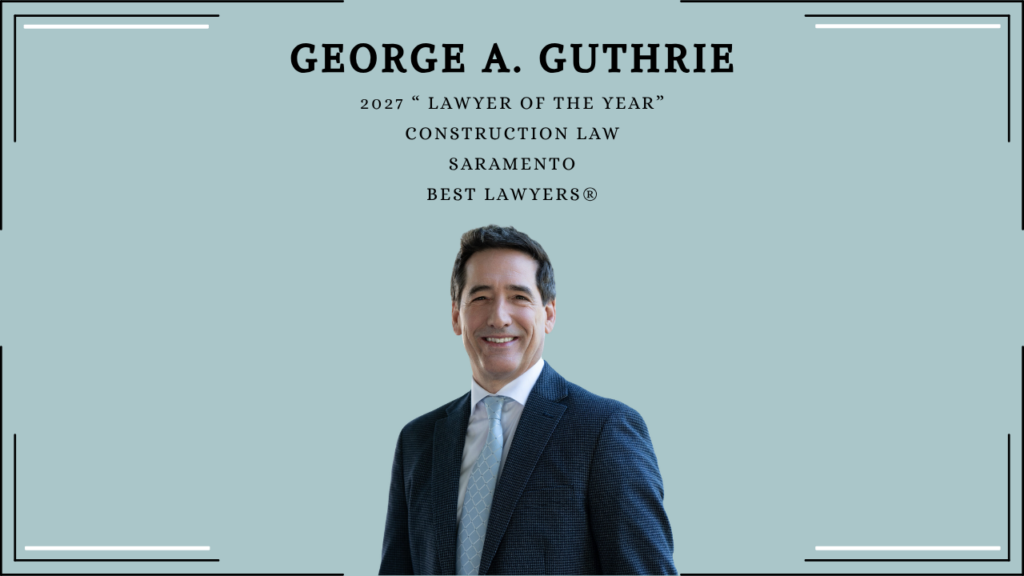
We’re proud to congratulate George Guthrie, named the Best Lawyers® 2027 Construction Law “Lawyer of the Year” in Sacramento.
“Lawyer of the Year” honors are awarded to one attorney in each practice area and metropolitan region based on the highest aggregate peer feedback.
Congratulations, George, on this outstanding recognition!
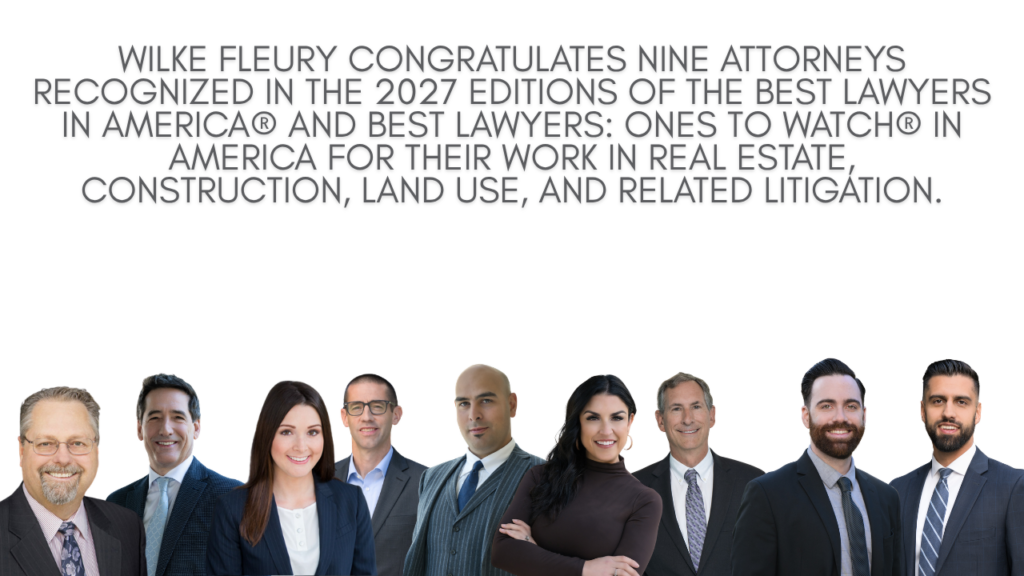
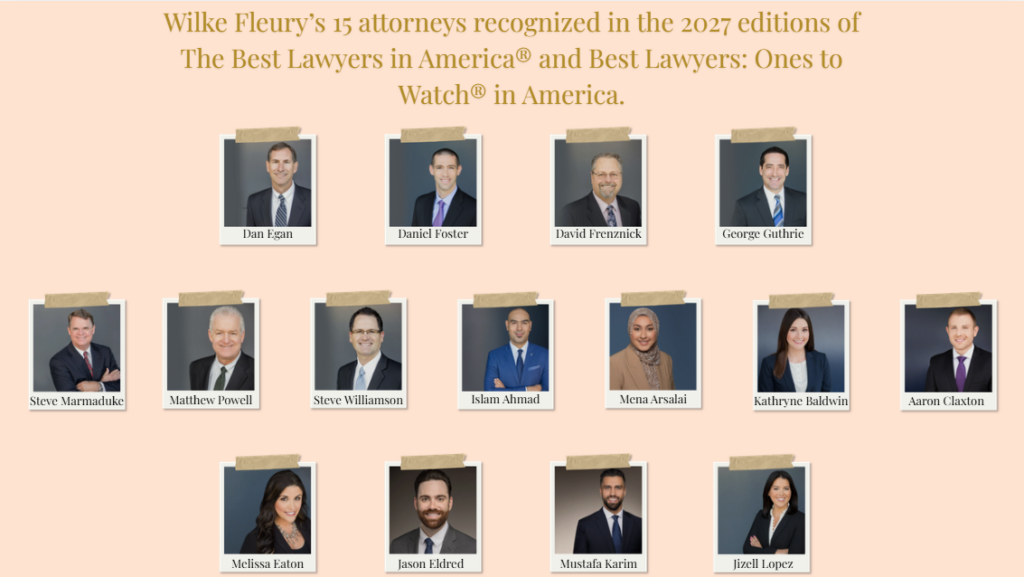
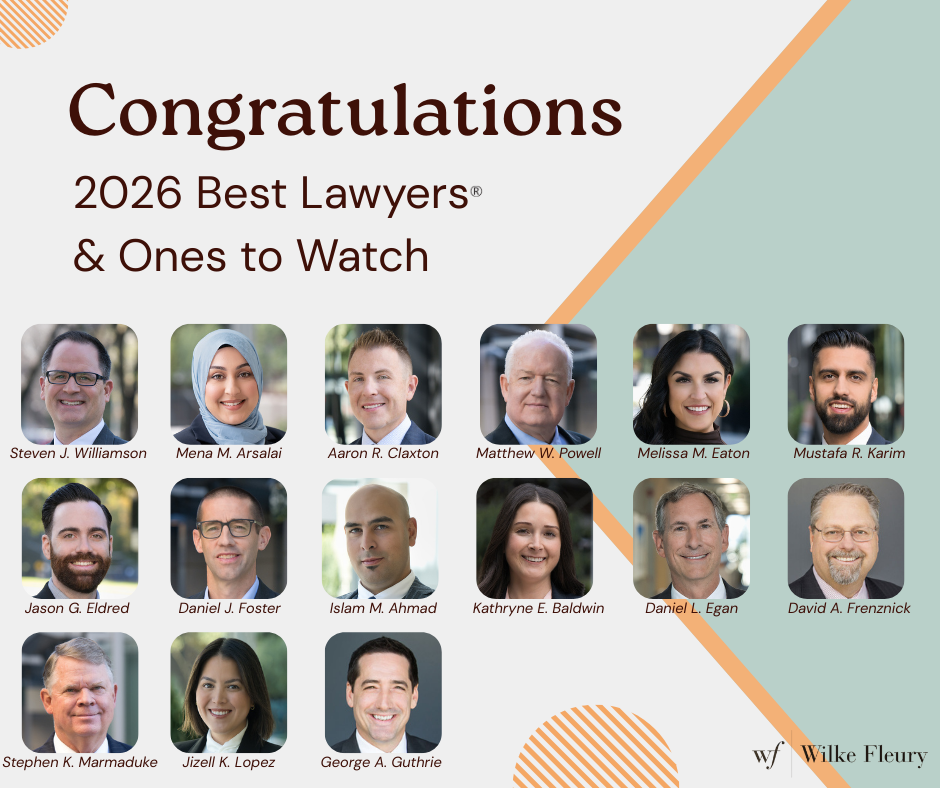
Congratulations to our 15 attorneys recognized in the 2027 editions of The Best Lawyers in America® and Best Lawyers: Ones to Watch® in America.
The Best Lawyers in America® Dan Egan — Bankruptcy and Creditor Debtor Rights / Insolvency and Reorganization Law; Commercial Litigation; Litigation – Bankruptcy; Litigation – Real Estate; Real Estate Law Daniel Foster — Construction Law; Litigation – Real Estate; Real Estate Law David Frenznick — Construction Law; Litigation – Construction; Litigation – Real Estate George Guthrie — Construction Law; Land Use and Zoning Law; Litigation – Real Estate; Real Estate Law Steve Marmaduke — Employment Law – Individuals; Employment Law – Management Matt Powell — Business Organizations (including LLCs and Partnerships); Commercial Litigation Steve Williamson — Bankruptcy and Creditor Debtor Rights / Insolvency and Reorganization Law; Commercial Litigation; Litigation – Bankruptcy
Best Lawyers: Ones to Watch® in America Islam M. Ahmad — Commercial Litigation; Litigation – Construction; Litigation – Real Estate; Real Estate Law Mena Arsalai — Health Care Law Kathryne Baldwin — Construction Law; Litigation – Construction; Litigation – Real Estate Aaron Claxton — Health Care Law Melissa Eaton — Real Estate Law Jason Eldred — Bankruptcy and Creditor Debtor Rights / Insolvency and Reorganization Law; Litigation – Bankruptcy; Litigation – Construction; Litigation – Labor and Employment; Litigation – Real Estate Mustafa Karim — Real Estate Law Jizell Lopez — Labor and Employment Law – Management
Best Lawyers recognitions are based on peer review, and we are proud to see the breadth of Wilke Fleury’s practices represented among this year’s honorees.
On May 7, 2026, Attorney General (“AG”) Rob Bonta filed a lawsuit on behalf of the people of California alleging that Aspen Dental Management, Inc. (“ADMI”) violated California Business and Professions Code sections 17200 et seq. and 17500 et seq. The parties have since agreed to a proposed Final Judgment, which now awaits approval from a superior court judge.
Monetary Payments
For alleged violations under Business and Professions Code sections 17206 and 17536, ADMI is required to pay $2 million in civil penalties, to be wired in full to the Office of the California Attorney General no later than 15 days following entry of the Judgment.
The settlement also requires ADMI to pay $300,000 in restitution to affected patients. Beyond the dollar amounts, the agreement specifies a detailed payment timeline and places an affirmative obligation on ADMI to reach out to eligible patients. In cases where patients cannot be located after good-faith efforts, any remaining restitution funds are to be remitted to the Office of the California Attorney General for disbursement to the Victims of Corporate Fraud Compensation Fund.
Injunctive Terms
The heart of this settlement lies in its injunctive relief. Spanning 46 subsections, these terms reflect AG Bonta’s firm line on what dental support organizations can and cannot do when operating in California. The settlement includes unprecedented injunctive terms to protect California consumers and clinical staff, covering everything from clinical independence to advertising transparency. Among the key restrictions, ADMI must not:
Replace any practice owner with a dentist of its own choosing
Require practice owners to surrender their dental practices upon termination of their contractual relationship with ADMI
Own the property used by any affiliated practice
Practice dentistry, including owning or managing any dental office
Base service fees on practice revenue, sales, or profits
Suggest, direct, or encourage any licensed clinician, other than a practice owner, to sell or increase revenue for any service or product
Compensate its own employees based on practice sales or revenue
Pay practice employees incentives tied to sales, revenue, profits, or the promotion of any particular service or product
Enforce existing contractual provisions that restrict where licensed clinicians may practice or limit their ability to communicate with patients they have treated
ADMI is also required to register with the Dental Board of California as a Dental Group Advertising and Referral Service, provide written fee schedules for products and lab services, and clearly identify the practice owner’s name in all advertisements, confer annually with the practice owner to negotiate the nature, scope, and service fees provided, among other provisions preserving the autonomy of practice owners over clinical and business decisions.
Compliance Provisions
Both the People and ADMI have mutually agreed to appoint an independent compliance monitor. The monitor will serve in this role for 36 months from the entry of the Judgment, the designated Oversight Period, with all associated costs to be paid by ADMI.
Three months after entry of the Judgment, the monitor must deliver a status report to the parties. Six months following that initial report, the monitor must complete a second written report reviewing ADMI’s compliance with any remaining outstanding terms. Throughout the Oversight Period, ADMI is required to provide the monitor with reasonable access to all records and employees.
Why This Settlement Matters: The Bigger Picture for Corporate Practice of Dentistry
Prohibition on the corporate practice of dentistry, the legal principle that prohibits non-licensed entities from owning or controlling dental practices, has existed in California law for decades (Bus. & Prof. Code, § 1626). The underlying concern is straightforward: when business interests are permitted to direct clinical decision-making, patient care can suffer. Incentive structures tied to revenue, centralized operational control, and restrictions on clinician autonomy all create an environment where profit can quietly override professional judgment. A trend the state actively targeted on October 6, 2025, when Governor Gavin Newsom signed Senate Bill No. 351 to curb private equity and hedge fund ownership in healthcare. This settlement is significant because it represents California’s most aggressive enforcement of that doctrine to date, and it does so at a moment when private equity investment in dental and medical practices is at an all-time high.
Owned by private equity firms, ADMI describes itself as a dental support organization that provides business management and administrative services to dental offices. The AG’s position, however, is that ADMI crossed the line from support into control, and the breadth of the injunctive terms suggests the office intends to hold that line going forward. For other dental support organizations and management services organizations operating in California, this settlement functions as both a warning and a roadmap. The 46-subsection injunction effectively illustrates the specific practices regulators are watching for: revenue-based fee structures, clinician incentive programs, real property ownership, and other restrictive covenants designed to insert corporate control into the practice of dentistry, precisely what California has moved to prohibit in healthcare. Whether or not a given Dental Service Organization (“DSO”) ‘s operations mirror ADMI’s, this settlement signals that California is no longer content to let organizational structure alone determine the boundaries of corporate practice. What matters now is how control is exercised in practice, and the AG’s office has made clear it is paying close attention.
So you finally finished your estate planning and signed your revocable living trust. Phew!! Now you are done. Or are you? Finalizing your trust is a major accomplishment to be applauded for sure. However, your trust is only effective as to assets “in the trust.” You will not avoid probate unless and until the trust obtains legal title to your property. The procedure of transferring title of your assets to your trust is called “funding” the trust and is a vitally important step in implementing your estate plan.
For an asset to be subject to the terms of your trust, you must transfer title to yourselves as trustees. In general, title on all trust assets should be held: “John Doe and Jane Doe, trustees of the John and Jane Doe Trust, dated _ _[date]_ _.”
Transferring title varies depending on the type of asset, but all transfers will require some documentation or “documents of title” be signed. The following is general guidance about common funding transfers, but there are nuances and variations so you should consult with your advisors to be sure the transfers are completed correctly:
1. Real property. To transfer your residence and other real property to the trust, you must execute a grant deed to the trustee(s) of the trust and then record the deed at the county recorder’s office (along with a Preliminary Change of Ownership Report). Again, the “grantee” on the deed will be in the form of “John Doe and Jane Doe, trustees of the John and Jane Doe Trust, dated _ _[date]_ _.”
Exception: If you purchase a home under the Cal-Vet program you should consult with the Department of Veterans Affairs for the proper method of transferring your contract.
2. Financial institution accounts. These accounts are normally transferred by changing the name of the account owner on the signature card or other “contract” between you and the bank, broker, etc., to the trustee of the trust. Financial institutions should be accustomed to making these transfers and generally have their own set of forms or documents to complete. Often, the institution will want a “certification of trust” and may ask that you complete their version. If not, your attorney can assist you with preparing one. It is highly recommended to visit the institution in person with a copy of your trust agreement than trying to do it over the telephone or on-line.
3. Stocks and bonds. If you hold your shares through a brokerage firm, you need change the title on the brokerage accounts. Your stockbroker may request a copy of the signed trust instrument for examination by his or her firm’s legal department. Again, this can be satisfied by a Certification of Trust which your attorney can help prepare for you as needed.
If you have physical stock/share certificates in your name, those certificates will have to be transferred which normally requires surrendering the certificates and having new certificates issued in the name of the trust. This process can be complicated and may involve working through a “transfer agent” so you should ask your advisors to assist you.
4. Automobiles. Generally, it is not necessary to transfer automobiles to the trust provided that you have given someone a durable power of attorney, which will enable them to sell the vehicle and transfer the proceeds to the trust if you become incapacitated or if you hold title with your intended beneficiaries as joint tenants. Also note that California law provides a procedure for an heir or other successor to the decedent’s property to transfer vehicle titles if the decedent has no other probate property and no probate proceeding is being conducted. The DMV has a form for certifying entitlement to transfers, titled “Affidavit for Transfer Without Probate; Titled Vehicle or Vessels Only.”
5. Other personal property. Since you generally do not have “title” documents for items such as your furniture, clothing, jewelry, etc, it is advisable to sign a general assignment to clearly indicate that you intend the trust to also hold all your tangible personal property.
6. Interests in businesses, including partnerships and small corporations. Transfers of interests in businesses will require an attorney’s assistance. Businesses generally require a variety of permits and licenses, and it is necessary that they be reviewed in detail before making the transfer. In addition, most business are held through an entity which may have owner agreements or other governing documents that need to be considered and complied with.
In addition to your current assets, moving forward you should take title to assets in your trust’s name as you acquire them. If you take title to an asset in your own name, that asset will not be a trust asset, undermining your planning.
If you have questions or need assistance with funding your trust, you should consult with experienced estate planning professional such as the Estate Planning Group at Wilke Fleury.
We are pleased to congratulate Jason Eldred on his promotion to senior counsel at Wilke Fleury LLP. Jason’s work in service of clients is outstanding. His thoughtfulness and hard work contribute so much to what makes our firm truly special. Jason’s clients include construction companies, real estate companies, and medical professionals. Jason’s practice focuses on business and healthcare litigation, employment counseling and litigation, and bankruptcy. Senior Counsel at Wilke Fleury have a minimum of six years experience delivering high-quality legal services, collaborating with partners on development and management of cases, and actively mentoring junior lawyers. Congratulations Jason!
Myth 1: I have a will, so I do not need anything else.
Fact: A will is one part of the estate planning puzzle. But it is only one part and by itself is generally insufficient to meet the comprehensive needs of a business owner. A will does not address what happens to your business if you become incapacitated (unable to handle your own affairs). A will does not avoid probate, leaving your loved ones to have to navigate the probate process after your death to transfer your business ownership interest. For everyone—but especially business owners—a comprehensive estate plan can help avoid delays, frozen assets, and legal battles. Relying on a will alone can leave your business vulnerable to disruption and potentially a significant loss of value.
Myth 2: My family will automatically take over the business if something happens to me.
Fact: Neither business ownership nor management automatically transfers to another person if you become incapacitated or pass away, unless you have taken formal steps and documented a legally binding transition process.
If you become incapacitated, your family cannot simply step in to run the business on your behalf. Without the proper estate planning tools in place, they may need to seek a court-appointed conservator, which can be time-consuming and costly, just to handle essential tasks for day-to-day management of your business, such as signing contracts, accessing business bank accounts, or approving payroll.
If you pass away without addressing the operation and transition of your business in your estate plan, the problems only multiply. Before your business interests can be transferred, there will likely have to be a probate proceeding —a public and often lengthy court process. Even worse, if you have done no estate planning, the court could determine who inherits your business interests according to state law, which may not be the person(s) you would have chosen. A relative with no interest or experience in running the business could end up in charge, or ownership could be split among multiple heirs, leading to disputes and instability.
A well-structured estate plan ensures that the right people are in control, operations continue smoothly, and your life’s work retains its value and purpose.
Myth 3: My business is small, so I do not need to worry about estate planning.
Fact: Even small businesses can face serious consequences without proper estate planning and may actually be more vulnerable than larger businesses because they often rely so heavily on the owner’s day-to-day involvement. If something happens to you and no one is legally authorized to act in your place, your business could lose access to contracts or bank accounts, miss payroll or tax deadlines, or even be forced to shut down. An estate plan ensures that someone you trust can step in immediately to make decisions, pay bills, and keep operations running, regardless of business size.
Wilke Fleury LLP is pleased to announce that Neal Lutterman is the firm’s Managing Partner beginning January 1, 2026. Neal succeeds Steve Williamson, who held the role of Managing Partner from 2020 through 2025. Steve Williamson led the firm through several years of significant change, and the firm is immeasurably grateful for Steve and his leadership.
Neal joined Wilke Fleury in 2015 and has been a Partner since 2017. Neal is an incredibly valuable member of the firm’s partnership and litigation teams. He has a demonstrated history of leadership on the firm’s Management Committee for 4+ years. Neal’s practice focuses on litigated matters in the healthcare arena. For over 25 years, Neal has defended physicians, healthcare systems, hospitals, medical groups, and allied healthcare providers in professional and general liability matters. Neal regularly represents physicians and other healthcare clients in administrative proceedings relating to professional licensing and disciplinary matters. Neal also works closely with the firm’s corporate healthcare clients representing health plans, Medicare Advantage Plans, Risk Bearing Organizations (RBOs), and other entities in reimbursement and contract disputes.
Neal will work closely with the firm’s Management Committee to advance the firm’s focus on client development, strategic growth, and attorney excellence in the years to come. Neal Lutterman is excited about the firm’s future, committed to the “next generation” of talented Sacramento lawyers, and continues to establish Wilke Fleury as the preeminent law firm in Sacramento.
On October 11, 2025, Governor Gavin Newsom signed Assembly Bill 1415 (“AB 1415”) into law. The bill amends the California Health Care Quality and Affordability Act by establishing reporting and notice requirements for certain “noticing entities” engaged in healthcare-related transactions, including private equity groups, hedge funds, management services organizations (“MSOs”), and newly formed entities created for the purpose of transacting with health care entities.
Effective January 1, 2026, AB 1415 formally codifies the category of “noticing entities” and mandates that all entities falling within this definition provide the Office of Health Care Affordability (“OHCA”) with written notice at least 90 days prior to entering into any transaction constituting a “material change” to the entity’s structure or operations.
Who Must Report?
In addition to the existing reporting obligations applicable to “health care entities,” AB 1415 extends notice requirements to any “noticing entity,” which includes all of the following:
A private equity group or hedge fund.
A newly created business entity formed for the purpose of entering into agreements or transactions with a health care entity.
A MSO.
An entity that owns, operates, or controls a provider, regardless of whether the provider is actively operating, providing health care services, or holds a current, pending, or suspended license.
AB 1415 defines MSO as “an entity that provides management and administrative support services for a provider in support of the delivery of health care services, excluding the direct provision of health services,” which may include “provider rate negotiation, revenue cycle management, or both.” AB 1415 also introduces definitions to “hedge fund” and “private equity group.”
What is Reportable?
A “noticing entity” must provide written notice to OHCA prior to engaging in a transaction with any payer, provider, or fully integrated delivery system that involves either of the following:
The sale, transfer, lease, exchange, option, encumbrance, conveyance, or other disposition of a material amount of the assets of a health care entity or an MSO; or
The transfer of control, responsibility, or governance over a material amount of the assets or operations of a health care entity or an MSO.
Additionally, MSOs must provide OHCA notice of any agreement or transaction described above when between the MSO and “any other entity.” This means MSOs must provide notice even when the other party is not a “noticing entity.”
Additional Reporting Requirement for MSOs
AB 1415 adds Section 127501.5 that authorizes OHCS to collect information from MSOs: “The office shall, in a manner prescribed by the office, establish requirements for management services organizations to submit data and other information as necessary to carry out the functions of the office.”
When Must Reporting Occur?
Notice must be submitted to OHCA at least 90 days before the parties enter into any reportable agreement or transaction.
How Does AB 1415 Impact Your Friendly-PC or MSO?
For newly formed friendly-PC structures, or for investors seeking to invest in healthcare entities through such structures, AB 1415 will require pre-closing notice to OHCA whenever the formation, acquisition, or execution of a management services agreement constitutes a material change transaction under the statute.
Existing friendly-PC or MSO arrangements are not subject to retroactive reporting; however, any new material change (e.g., a sale, transfer of equity or governance rights, restructuring, refinancing, or recapitalization) will trigger the 90-day notice requirement. As a result, even routine ownership or organizational adjustments may face added regulatory steps and potential delays.
If you have further questions in anticipation of the January 1, 2026 effective date, please contact the healthcare team at Wilke Fleury.
1. A partridge in a pear tree. Female partridges are among a group of clever birds known to feign injury as a way to lure predators from their nest and protect their young. Think of yourestate plan as the human version of that instinct—a clever way to protect and reduce risk for your own loved ones.
Estate planning step: Schedule meetings with your financial advisor and estate planning attorney to discuss your priorities, values, and needs. Laying this groundwork ensures that every step that follows serves your core objectives. Be prepared to discuss family dynamics and special circumstances; pinpoint your legal objectives (e.g., minimizing estate taxes or avoiding probate); and determine which financial and estate planning strategies best meet your needs.
2. Two turtle doves. Turtle doves often serve as a symbol of devotion. A comprehensive estate plan that includes everyone you value in your life can demonstrate your own level of commitment to those closest to you.
Estate planning step: Before meeting with your advisor and attorney, gather your personal, financial, and family information, including names, birthdates, and contact information for your children, stepchildren, spouse, siblings, and other loved ones. Consider involving your spouse or your closest family members early in the process. Including them early helps ensure that everyone understands your intentions, avoids misunderstandings, and reduces the risk of surprises or conflict later.
3. Three French hens. In the famed Christmas carol, the three French hens are commonly associated with the virtues of faith, hope, and generosity. In seeking to safeguard your own nest egg for the next generation, consider what hopes you may have for their future as well as whom you would trust most to carry out your wishes.
Estate planning step: Take time to identify your beneficiaries and understand their individual needs—financial, emotional, or otherwise. Knowing what you want to support in each person’s life helps shape a plan that is both practical and meaningful. But do not stop there; think carefully about whom you trust to carry out your wishes, since the success of your plan depends on choosing the right people to fulfill your intentions when the time comes.
4. Four calling birds. Some historians assert that the song lyrics originally referenced “colly” birds,[1] an archaic term for blackbirds. Highly territorial, blackbirds stand ready to defend their home under any circumstances. Once you have a clear picture of what you wish to protect, you will also be able to secure all that you hold dear.
Estate planning step: Prepare an inventory of everything you own and owe, including a complete list of your assets (e.g., accounts and property), income information, and existing insurance policies, as well as your debts. Have this information organized and ready to share at your meetings with your advisor and attorney, ensuring you can effectively defend and protect your loved ones through your estate plan.
5. Five golden rings. According to some researchers, the gold rings from the “Twelve Days of Christmas” song do not signify jewelry but the name of yet another bird, the goldfinch.[2] A resilient and adaptable songbird species, the goldfinch reminds you to be prepared to weather any of life’s unpredictable events.
Estate planning step: Preparing for the unexpected means considering many possible scenarios. Your estate plan should be flexible enough to adapt as your life, family, and finances evolve. Before meeting with your advisor or attorney, review any recent life changes, such as births, deaths, marriages, or the acquisition of new assets, and consider how your goals may shift over time. This will enable your plan to be designed to grow and adapt with you.
6. Six geese a-laying. Some pinpoint the six geese in the song as representing creation and new life. Similarly, think of estate planning not as gloomy or morbid but as a forward-looking act of creating new opportunities and protections for those who come after you.
Estate planning step: An estate plan encompasses more than distributing your money and property after you have passed away. Creating a thoughtful plan that passes your wisdom and values on to your beneficiaries can prove just as meaningful. Think about what family histories, stories, or personal philosophies feel crucial to share with the next generation. You may consider including these in a legacy letter that accompanies your estate plan. Taking this step not only strengthens your legacy but also provides new opportunities and perspectives for the next generation to build upon.
7. Seven swans a-swimming. The number seven is often regarded as sacred in many religions and cultures. In Catholicism, it has often been tied to completeness or perfection. While no one is perfect, you can work with advisors and estate planning professionals to ensure that your estate plan is as complete and legally solid as possible.
Estate planning step: Finalizing and signing your estate planning documents is essential to ensure that they are legally valid and enforceable. Because requirements for witnesses, notarization, and execution vary by state, working with a qualified professional helps ensure that your documents meet all legal standards and reflect best practices in your jurisdiction.
8. Eight maids a-milking. The milkmaid in the lyrics has elicited a range of interpretations throughout history, including portrayals of diligence, humility, and dignity in everyday tasks. At first glance, estate planning may seem to be of interest only to those with significant wealth, but in reality, it is a process from which everyone can benefit, regardless of the size of their estate.
Estate planning step: Focus on your goals, not just your net worth. Like the milkmaid who found meaning in her everyday work, view your estate plan as a way to care for the people and values that matter most—both during your lifetime and after your death. A well-crafted plan can also guide and protect you during periods of incapacity (being unable to handle your own affairs), ensuring that your daily life and decisions continue to reflect your wishes.
9. Nine ladies dancing. Whether the nine ladies in the song symbolize angels or virtues such as love, joy, and patience remains uncertain. Either way, they serve as a reminder to take the necessary steps in the estate planning process. It may initially seem intimidating or hard to follow, but with guidance from your advisor and attorney, all components of your plan will ultimately align.
Estate planning step: Partner with a professional to master all the right estate planning moves. If you establish a trust-based estate plan, be sure to fund the trust, i.e., transfer assets into it, so it actually works as intended and avoids probate. Another smart move is to keep your beneficiary designations up-to-date, ensuring that your accounts align with the rest of your plan.
10. Ten lords a-leaping. The leaping lords remind us to lift others up and stay connected during the holidays. Joy grows when it is shared, especially with those who may need extra support or encouragement.
Estate planning step: Taking the lead involves helping those around you. In estate planning, communicate the key elements of your plan to all key partners involved in the process, including your fiduciaries and beneficiaries. Ensure that they are aware of the location of your documents, who is responsible for what, and what you expect from them. By involving your loved ones in the conversation, you provide them with clarity about your wishes and ensure that they are supported when life feels uncertain.
11. Eleven pipers piping. Estate planning can help maintain harmony among your loved ones. You are the composer, and your financial accounts, property, and personal possessions are all instruments that play a role in your plan. A well-structured estate plan that accurately reflects your intentions can facilitate a smooth transfer of assets to your beneficiaries.
Estate planning step: Once you have completed your carefully curated “playlist” of estate planning documents, store your plan securely (both physically and digitally), and maintain a summary or index that helps your loved ones quickly find what they need.
12. Twelve drummers drumming. Getting into a consistent rhythm as the seasons of your life shift means less stress and more time for celebration and enjoyment.
Estate planning step: Set a regular review schedule—annually or after major life events such as marriage, birth, or a move—to keep your plan current with your life and the law.
The Greatest Gift You Can Give
Knowing where something came from, whether a song, a family tradition, or a personal value, deepens its meaning. The same principle applies to your estate plan.
To create a plan that truly reflects who you are and what you care about, your advisor and attorney need to understand your history, relationships, and goals. It may take longer than 12 days to create your plan once we have all the necessary information, but you will have a gift far more valuable and lasting than anything found under the tree.
This holiday season, as you reflect on the year and spend time with loved ones, you can take real steps toward securing your family’s future—one meeting, one conversation, and one thoughtful gift at a time. Please call us to schedule a time to create or review your existing estate plan.
The Department of Managed Health Care (DMHC) held its quarterly roundtable on September 3, 2025. Mental health and behavioral health were central topics, with significant focus on 988 crisis services and employee assistance programs (EAPs). While much of the discussion was directed at full-service health and behavioral health plans, DMHC emphasized that the lessons extend to all licensees. Dental plans, vision plans, and other specialized entities should pay close attention to these developments because the Department’s regulatory expectations now apply across the market.
Crisis Services and the 988 Hotline
A major theme was the handling of crisis response under the 988 hotline. DMHC explained that crisis services must be covered without prior authorization until an individual is stabilized. Once stabilization occurs, the provider must either obtain authorization or transfer the member to an in-network facility. This approach is designed to ensure that people in crisis receive timely help without administrative barriers. DMHC also clarified that counties are not permitted to bill commercial plans directly for mobile crisis services, except in cases of crisis stabilization. Earlier this year, the Department issued All Plan Letter 25-006 with billing codes, and it is now working with county Behavioral Health Directors to conduct training in all 58 counties. These efforts aim to ensure consistent billing and payment practices.
Broader Application to All Plans
Although these requirements are often associated with behavioral health, DMHC was clear that the same expectations apply to all licensees. Plans must have internal protocols that prevent improper billing, avoid disruptions in care, and provide smooth coordination for enrollees who need crisis services. The central message is that plans are expected to adopt practices that protect members in moments of crisis.
Clarifying the Role of EAPs
The Department also devoted attention to EAPs. These programs often serve as a first entry point for members in distress, yet they can create confusion about where coverage ends and where behavioral health benefits begin. DMHC has stated that plans must help enrollees transition from EAP sessions into ongoing behavioral health treatment when necessary. Member-facing materials must clearly explain coverage boundaries and referral pathways. Employers that provide EAPs should also confirm that employees understand what is included in these programs and what steps to take when additional care is needed.
Network Adequacy and Health Equity
In addition to these immediate issues, DMHC is advancing broader initiatives around network adequacy and health equity. New standards for provider ratios, geographic access, and block transfers have already been released and will soon be incorporated into regulation. At the same time, DMHC is developing health equity regulations that are scheduled to take effect on January 1, 2027. These regulations will require all plans to report disparities in access and outcomes and to demonstrate corrective action. Behavioral health is likely to remain a central focus, but the rules will extend across all benefit categories. For enrollees, these changes should improve wait times and expand provider options. For plans, they create new responsibilities to evaluate networks and implement equity reporting systems.
The Path Forward
The overall takeaway from the September roundtable is that DMHC intends to hold every plan to consistent and measurable standards. Whether a plan is medical, dental, vision, or another type of specialized licensee, the Department expects compliance, transparency, and accountability. Plans that begin aligning their protocols and communications now will not only stay ahead of regulatory deadlines but will also improve the enrollee experience. DMHC is treating behavioral health compliance as a model for how it will regulate the entire health plan market.
The Department’s message was clear: health plans should not wait for enforcement action before making changes. Those that review their crisis protocols, clarify the boundaries of EAP coverage, and begin preparing for health equity reporting will be better positioned to demonstrate compliance and build trust with their enrollees.
Wilke Fleury is extremely proud to have seven attorneys recognized in The Best Lawyers in America and eight attorneys recognized in the Best Lawyers: Ones to Watch in America! Best Lawyers has been regarded by lawyers and the public for more than 40 years as the most credible measure of legal integrity and distinction in the United States. Congratulations to this talented group!
California is a litigious landscape; it is one of the most heavily regulated and litigious states in the country. Businesses both small and large face a complex web of employment laws, consumer protection statutes, environmental regulations, and contractual obligations – most of which come with heavy-handed penalties for non-compliance. In this environment, the best defense is a robust offense. Businesses that invest internally in thoughtful structuring, clear internal protocols, and regular legal check-ins position themselves well to avoid litigation altogether or, at the very least, to withstand it. Facing litigation can be a reality in today’s world of catchy headlines of big-time judgments, so it is important to follow some time-tested rules to best arm your business if the day comes where it needs to defend itself.
First Rule of Litigation: Documentation – It will not be surprising to learn the best way to protect your business against what feels like inevitable litigation, is documentation. Whether it is your time clock entries, communications with vendors or clients, clear, written documentation that complies with California law creates a record that can make or break a defense. If you do have something like an employment handbook, do not rest on the laurels of that accomplishment. Have it reviewed regularly to be sure it reflects compliance with current legal standards. Doing so means you close common loopholes that billboard and bus stop plaintiff attorneys are familiar with exploiting.
Second Rule of Litigation: Have Legal Counsel Before You Need It – Successful businesses, or businesses that last, do not wait for a someone to file a lawsuit before looking for legal counsel. Once service of a complaint takes place, the clock on your time to respond starts; each day spent trying to find competent counsel ticks away precious days that should be spent analyzing and strategizing the best defense. Stalwart businesses foster an ongoing relationship with attorneys who understand their individualized business model, pressures facing their specific industry, and comfort level with risk tolerance. Consulting with counsel on an ongoing basis ensures day-to-day decision making runs as smoothly as possible and allows for candid conversations about liability exposure. Additionally, business owners with counsel already on board save themselves the apprehension if a lawsuit ever arises.
Third Rule of Litigation: Insurance Coverage – Make sure you have the insurance coverage you think you do before an employee, client, or party to a contract files suit. Too often, businesses under-insure or do not have coverage for conduct they think they do. Reviewing your commercial general liability policy, employment practices liability insurance, cyber insurance, and directors and officers coverage with your attorney or your insurance broker helps ensure your coverage is aligned with the actual risk profile of your business. For example, many contractors find out after the fact their policy does not cover claims of poor workmanship; once litigation is filed, it is too late to rectify that problem. Having proper insurance coverage to start with makes it easier to tender a defense quickly and get an insurance company to participate in the litigation on your behalf, when required to do so.
Taking proactive steps to protect your business from litigation in California is not just smart – it is essential. By maintaining documentation, engaging legal counsel before disputes arrive, and ensuring your insurance coverage aligns with your risk profile, you can significantly reduce exposure and respond more effectively if a claim is made. A little preparation today can save your business time, money, and stress down the road.
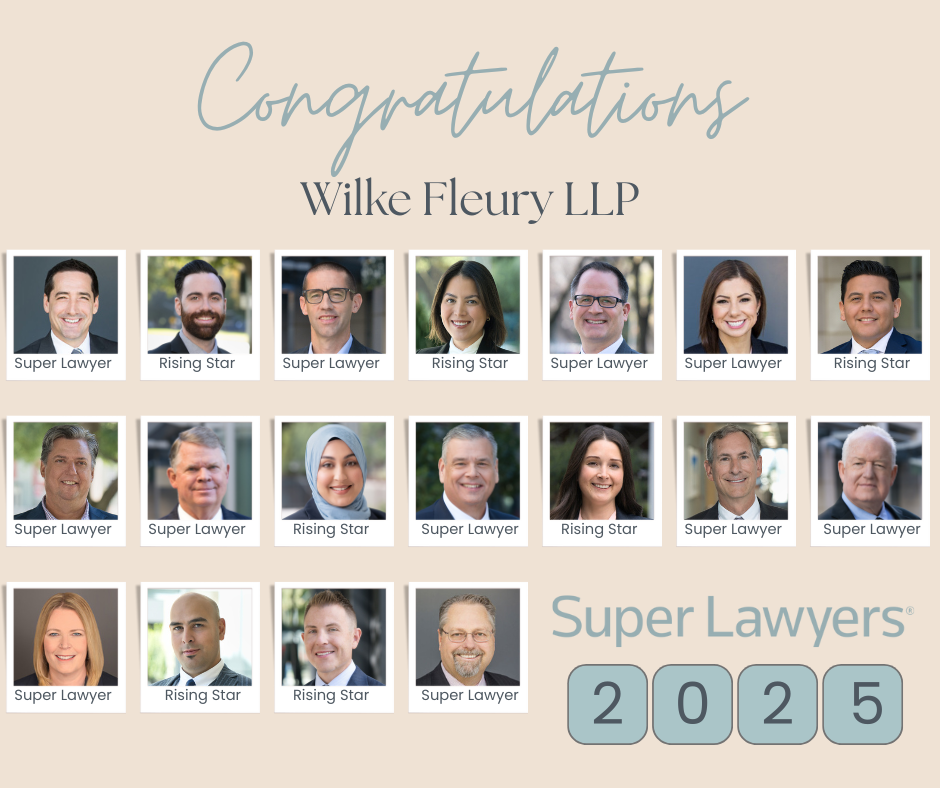
Wilke Fleury is extremely proud that several of its incredible attorneys have been selected as 2025 Northern California Super Lawyers or Rising Stars! Super Lawyers rates attorneys in each state using a patented selection process and publishes a yearly magazine issue that produces award-winning features on selected attorneys. Congratulations to this talented group:
Wilke Fleury exists to solve clients’ business needs. Committed to intellectual excellence and critical thinking, Wilke Fleury lawyers apply meaningful analysis to even the most complicated business needs. From entity formation, M&A, restructuring, agri-business, healthcare, real estate, labor & employment, litigation defense, and wealth management, Wilke Fleury is focused on solutions, strategy, responsiveness and fierce advocacy. Wilke Fleury is the firm for all businesses seeking thoughtful, skilled attorneys to advocate and guide.
This website uses cookies to improve your experience. We'll assume you're okay with this, but you can opt-out if you wish. Cookie SettingsACCEPT
Privacy & Cookies Policy
Privacy Overview
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. This category only includes cookies that ensures basic functionalities and security features of the website. These cookies do not store any personal information.
Any cookies that may not be particularly necessary for the website to function and is used specifically to collect user personal data via analytics, ads, other embedded contents are termed as non-necessary cookies. It is mandatory to procure user consent prior to running these cookies on your website.